Setting Up
Hong Kong company checklist: your first 90 days after incorporation
A Hong Kong company checklist for the first 90 days: significant controllers register, filing time limits, bank account, bookkeeping, MPF and employer returns.

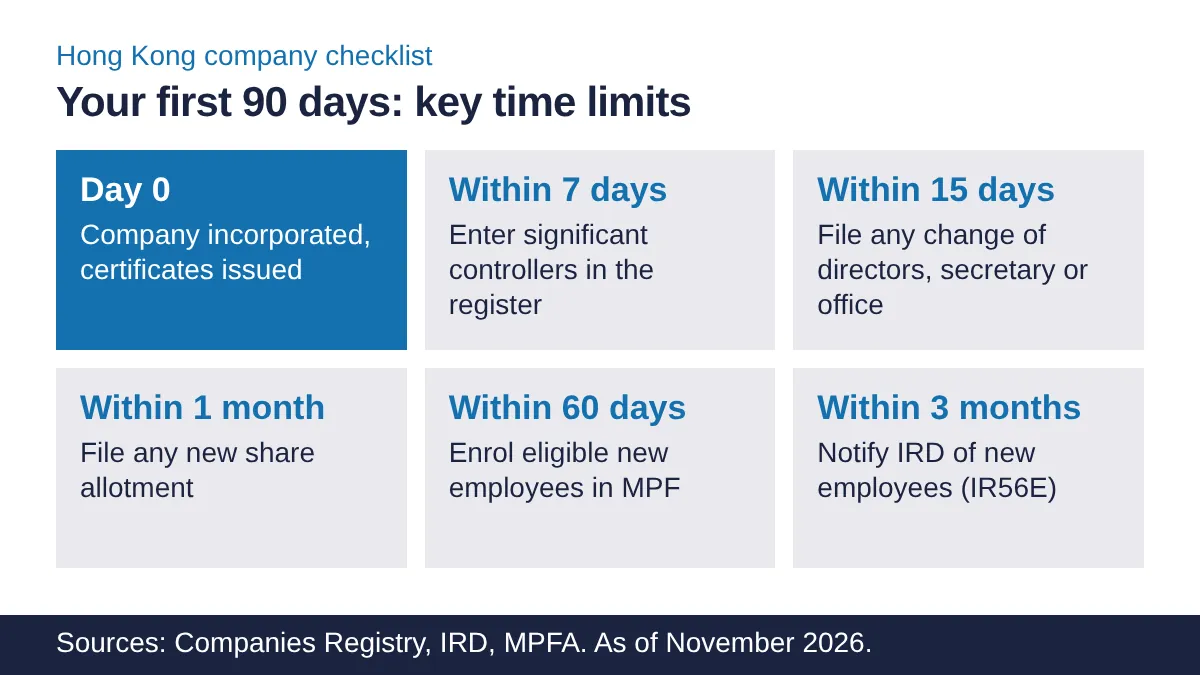
Your certificates have arrived and your Hong Kong company exists. The next three months decide how smoothly it runs. Most problems for overseas owners start here, with a register that was never set up or a change that was never filed. This checklist covers the first 90 days, with the official time limits as of November 2026. If you have not incorporated yet, start with our guide to setting up a company in Hong Kong as a foreigner.
What should you do in the first week after incorporating a Hong Kong company?
Set up the statutory records and the people who keep them. Start with the significant controllers register, the designated representative and the company secretary.
Every Hong Kong company except listed companies must identify its significant controllers and keep a register. If there are none, the register must say so. Particulars must be entered within 7 days after the controller has confirmed them. The company and each responsible person can be fined up to HK$25,000, plus a daily fine of HK$700 where applicable, for failing to keep it.
The register is not filed with the Companies Registry. It is kept at the registered office or another place in Hong Kong. If it is kept elsewhere than the registered office, the company files Form NR2 within 15 days.
The company must also designate at least one representative to give information about the register. This person must be one of:
- A Hong Kong-resident director, shareholder or employee.
- An accounting professional or legal professional.
- A licensed trust or company service provider.
The company secretary must ordinarily reside in Hong Kong if an individual, or have a registered office or place of business in Hong Kong if a company. Many overseas owners use a company secretary service for both roles, with records held at the company's registered office.
Which changes must be filed with the Companies Registry, and how fast?
Most changes have a 15-day limit. Early on, founders often add a director, move the office or issue more shares, and each one triggers a filing.
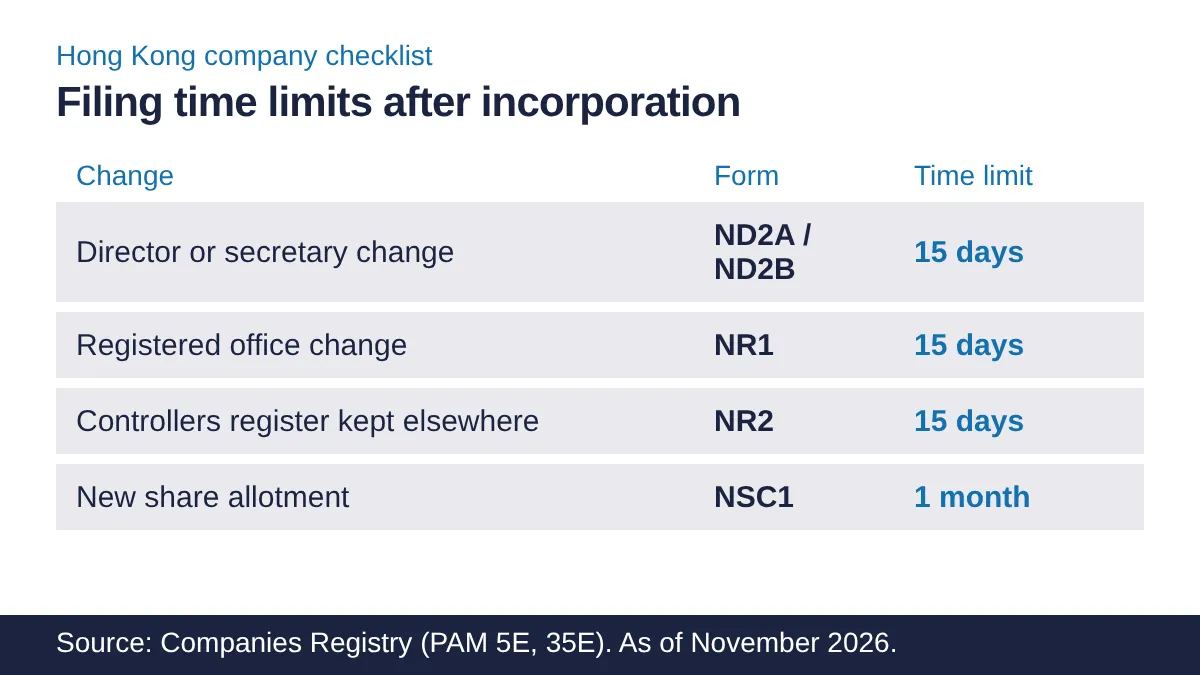
| Change | Form | Time limit |
|---|---|---|
| Appointment or cessation of a director or secretary | ND2A | Within 15 days |
| Change in a director's or secretary's particulars | ND2B | Within 15 days |
| Change of registered office | NR1 | Within 15 days |
| Allotment of new shares | NSC1 | Within one month |
Keep the company's own registers of directors and members up to date at the same time. A bank will ask for them during account opening.
When should you open the bank account?
Start in the first month. The bank account usually takes the longest of any step, and you cannot trade properly without it.
Banks review the company's ownership, its business and where money will come from. Prepare the certificates, the registers, identity documents and evidence of real business such as contracts or invoices. Our guide to opening a Hong Kong bank account as a non-resident explains what banks look for. If you will collect money from many countries, plan your cross-border payment setup alongside the bank account.
How should you set up bookkeeping in the first 90 days?
Choose a system and a financial year-end now, and record every transaction from day one. Every Hong Kong company needs an annual audit, and clean records make it faster.
A few early decisions save time later:
- Pick an accounting year-end that suits your group and home-country reporting.
- Keep company money separate from personal money from the first payment.
- Save invoices, receipts, contracts and bank statements in one place.
- Decide who will prepare monthly accounts and who will arrange the audit.
Our article on Hong Kong audit and accounting requirements explains the yearly audit. Profits tax is charged at 8.25% on the first HK$2 million of assessable profits and 16.5% above that, so tracking profit early also helps with planning. Our accounting service can keep the books from the first month.
What are your duties if you hire staff in Hong Kong?
Two deadlines apply from the first hire. Enrol eligible staff in MPF within 60 days, and notify the Inland Revenue Department within 3 months.
Employers must enrol employees aged 18 to 64 who are employed for a continuous period of 60 days or more in an MPF scheme. Enrolment is due within the first 60 days of employment, unless the employee is an exempt person. The Inland Revenue Department requires form IR56E within 3 months of employing someone likely to be chargeable to salaries tax.
Later in the year, an employer's return arrives in early April and must be filed within one month. When someone leaves, file form IR56F one month before the employment ends.
What deadlines come after the first 90 days?
The first annual return is the next fixed date. A private company must deliver it within 42 days after the anniversary of its incorporation.
The Registrar cannot extend this deadline, and late filing is a criminal offence with higher fees. The Companies Registry offers an e-Reminder service and a filing calculator. Our Hong Kong annual compliance calendar lists the full yearly cycle. If you plan to run everything from abroad, our guide to running a Hong Kong company remotely explains what must stay local.
Owners in the United States, the United Kingdom and South Africa may also have home-country reporting for a company they own abroad. The rules differ by country, so ask a home-country adviser early. A small group should also know that the new global minimum tax applies only to very large groups.
Frequently asked questions
What should I do first after my Hong Kong company is incorporated?
Set up the company's statutory records, including the significant controllers register and a designated representative, then start the bank account application and a bookkeeping system. These steps make every later filing easier.
Does my significant controllers register have to be filed with the Companies Registry?
No. It must be kept at the registered office or another place in Hong Kong and shown to law enforcement on request. If it is kept somewhere other than the registered office, the company must notify the Registrar on Form NR2 within 15 days.
Who can be the designated representative of a Hong Kong company?
A Hong Kong-resident director, shareholder or employee, or an accounting professional, legal professional or licensed trust or company service provider. The company must designate at least one.
When must I enrol a new employee in MPF?
Within the first 60 days of employment, for employees aged 18 to 64 employed for a continuous period of 60 days or more, unless they are exempt persons.
Sources
- Companies Registry: Filing requirements of a local limited company after incorporation (PAM 5E, May 2025)
- Companies Registry: Keeping of significant controllers registers (PAM 35E, May 2025)
- Inland Revenue Department: What tax obligations do I have as an employer?
- Mandatory Provident Fund Schemes Authority: Enrolment for employees
This article is general information, not legal or tax advice. Rules and figures can change; confirm details for your situation before acting.