Setting Up
Hong Kong annual compliance calendar for overseas company owners
Hong Kong annual compliance calendar for overseas owners: annual return, AGM, profits tax and employer's returns, business registration and key 2026 deadlines.

Owning a Hong Kong company from abroad is simple once you know the rhythm of the year. Most deadlines repeat on the same dates, and most problems come from mail that sits unread at a registered office. This calendar sets out the yearly filings, as of November 2026, with one deadline that falls next week.
What are the main yearly deadlines for a Hong Kong company?
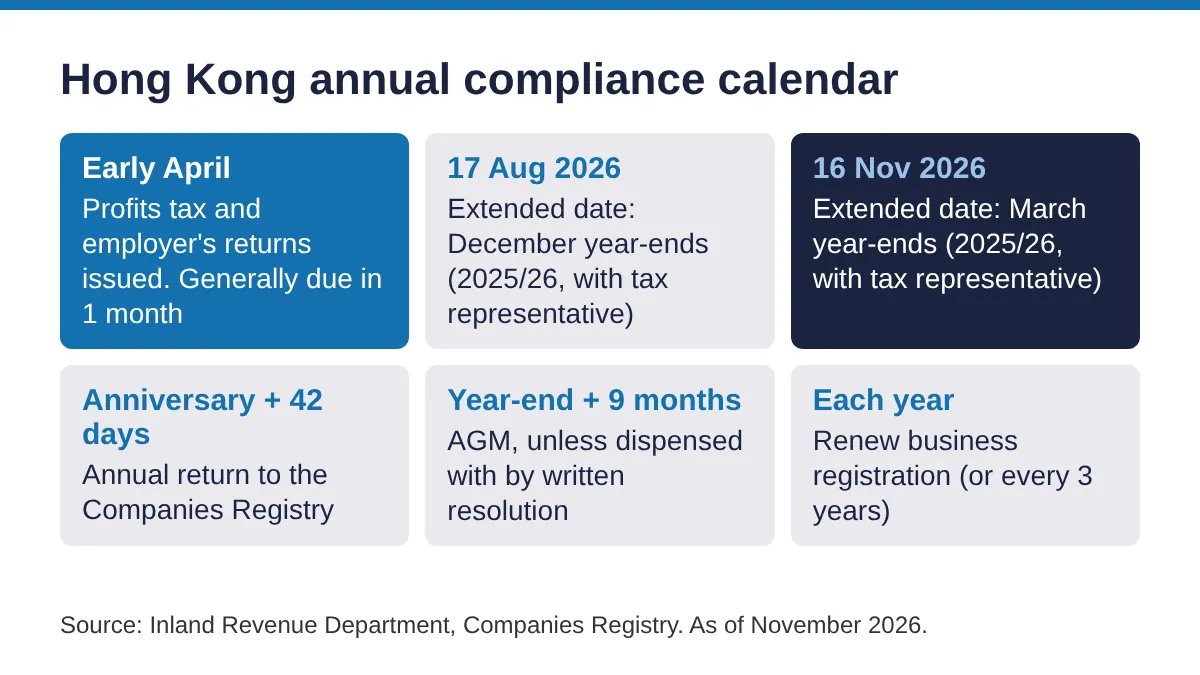
A Hong Kong private company has five yearly obligations: the annual return, the profits tax return, the employer's return, the AGM or its written-resolution alternative, and business registration renewal.
| Obligation | Who it goes to | When it is due (as of November 2026) |
|---|---|---|
| Annual return | Companies Registry | Within 42 days after each anniversary of incorporation |
| Profits tax return | Inland Revenue Department | Issued early April; generally due within one month, later with a tax representative |
| Employer's return | Inland Revenue Department | Issued early April; due within one month, even with no employees |
| AGM | Shareholders | Within 9 months after the end of the accounting reference period |
| Business registration | Inland Revenue Department | Renewed each year, or every three years if you choose a three-year certificate |
The dates for your company depend on two choices made at the start: the incorporation date and the financial year-end. Our guide to setting up a company in Hong Kong as a foreigner explains both.
When is the annual return due, and what if it is late?
A private company must deliver its annual return within 42 days after the anniversary of its incorporation. This does not apply in the year of incorporation. Sundays and public holidays count toward the 42 days.
The fee is HK$105 if the return is on time. Late returns pay a much higher fee that rises with time:
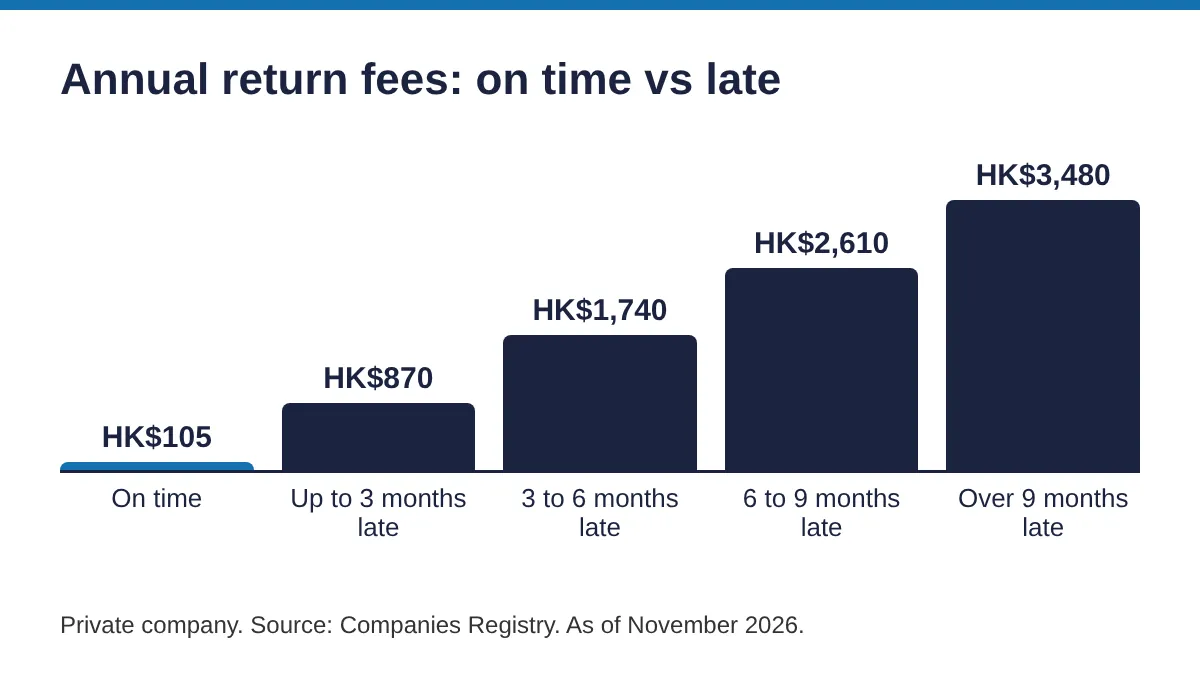
- On time: HK$105.
- Up to 3 months late: HK$870.
- More than 3 and up to 6 months late: HK$1,740.
- More than 6 and up to 9 months late: HK$2,610.
- More than 9 months late: HK$3,480.
The annual return also confirms the company's directors, secretary and shareholders. A company secretary normally prepares it and tracks the date for you.
When are profits tax returns due?
The Inland Revenue Department issues profits tax returns in early April, and returns are generally due within one month of issue. On 1 April 2026 it issued about 270,000 profits tax returns for 2025/26.
Companies that appoint a tax representative get later dates under the block extension scheme. These depend on the accounting year-end:
| Year-end code | Accounting year ending | 2025/26 extended due date |
|---|---|---|
| N | 1 April to 30 November 2025 | No extension |
| D | 1 to 31 December 2025 | 17 August 2026 |
| M | 1 January to 31 March 2026 | 16 November 2026 |
If your company has a March year-end and a represented return still open, 16 November 2026 is the date to watch. Loss-making "M" code cases can apply for an extension to 1 February 2027, with individual requests lodged by 16 November 2026.
First-year returns are different. A newly incorporated company can file its first return within 3 months of the date it was issued. Corporations with gross income must file their financial statements and tax computation with the return, and audited financial statements are generally required. Our accounting and corporate tax teams usually handle this as one workflow. For how the rates work, see our guide to the two-tier profits tax.
What are the employer and payroll deadlines?
The employer's return is issued in early April and must be filed within one month of receipt. This applies even if the company has no employees, has not started business or has ceased business.
Hiring staff in Hong Kong adds event-based deadlines:
- New employee. Notify the IRD within 3 months of employing someone likely to be chargeable to salaries tax.
- MPF enrolment. Enrol eligible employees aged 18 to 64 in an MPF scheme within the first 60 days of employment.
- Leaving employment. Notify the IRD one month before an employee's employment ends.
- Leaving Hong Kong. Notify the IRD one month before an employee's expected departure, and withhold money due to them until the IRD issues a letter of release.
Does a Hong Kong company still need an AGM?
A private company that is not a subsidiary of a public company must hold its AGM within 9 months after the end of its accounting reference period. It can avoid holding one in three ways.
- It can pass a written resolution to dispense with AGMs.
- It can use a written resolution covering everything the AGM would do, with the required documents sent to every member in time.
- A single-member company does not need to hold an AGM at all.
General meetings can also be fully virtual or hybrid. That makes the AGM a manageable task for owners who live abroad. Our article on running a Hong Kong company remotely covers what else can be done from overseas.
How do overseas owners keep the calendar under control?
Most missed deadlines start with a letter nobody opened. A short routine prevents that.
- Set the two anchor dates. Note your incorporation anniversary and your financial year-end. Almost every other date follows from them.
- Route official mail. Tax returns go to the registered office. Ask your registered office provider to scan and flag them on arrival.
- Appoint a tax representative early. It gives you the extended block extension dates and one point of contact with the IRD.
- Keep registers current. The significant controllers register must be kept in Hong Kong, at the registered office or another local place notified to the Companies Registry.
- Check business registration. Decide between one-year and three-year certificates; a switch must be made at least one month before the current certificate expires.
Frequently asked questions
When is a Hong Kong company's annual return due?
A private company must deliver its annual return within 42 days after the anniversary of its incorporation each year, except in the year it was incorporated. The fee is HK$105 if delivered on time.
When is the Hong Kong profits tax return due?
Returns are issued in early April and are generally due within one month. Companies using a tax representative get extended dates under the block extension scheme. For 2025/26, March year-ends had until 16 November 2026.
Does a Hong Kong company need to hold an AGM?
A private company must hold an AGM within 9 months after the end of its accounting reference period. It can dispense with AGMs by written resolution, and a single-member company does not need to hold one.
Do I need to file an employer's return if I have no staff?
Yes. The IRD asks companies to file the employer's return within one month of receipt even if they have no employees or have not started business.
Sources
This article is general information, not legal or tax advice. Rules and figures can change; confirm details for your situation before acting.